Wednesday, October 7, 2026ArchiveSearchAsk the paper

The Computomatix Times

All the posts fit to save — curated from @computomatix's bookmarks & likes on X

Analyst Argues Agentic Commerce Threatens Amazon's Ad Business

Freda Duan argues that agentic shopping agents could disintermediate Amazon's roughly $100 billion ad business and erode its customer relationship, while Amazon's logistics could open a new revenue stream. She also contends ad spend and take rates will converge, citing OTA economics, and links to a deep dive on the topic.

Original post · 2 min read
Largely agree.

1/ Agentic commerce's impact on $AMZN

Ads rev ($100B rev, or est. 50% of operating profit): real disintermediation risk.

GMV: depends. If $AMZN is truly "cheaper, faster, better", an objective agent should send more GMV to $AMZN. But I personally doubt $AMZN’s GMV share grows meaningfully in an agentic world. Just look at the $50B in marketing exp. $AMZN throws out today - large platforms have an "unfair advantage" bc they can afford higher CAC.

Long-term value / customer ownership: intrinsic value should go down if $AMZN loses the top of the funnel. You may still get the trx and the buyer’s info, but you lose browsing behavior, retargeting, cross-sell opps, and ultimately the customer relationship.

Potential upside: $AMZN can open up its best-in-class logistics backbone to other merchants = new rev stream (which it is already doing a little).

The risk feels more skewed to the downside, imho: top of funnel → infrastructure layer.

2/ What happens to ads as an industry

Under agentic commerce, ad spend and take rate - which ppl historically think of as distinct business models - will converge.

In a fully agentic world, ads as an industry could theoretically "disappear." But that doesn’t mean the ad dollars (~$300B in the US) disappear. Sellers will still need (and want) to pay digital tax on distribution. Whether that comes in the form of ads or a take rate is largely semantic.

Take OTAs ($BKNG $EXPE) as an example. Say half of their bookings and traffic are direct, and the other half indirect, mostly through $Google. For the indirect portion, the companies basically break even given the high CPCs they pay $Google. Take rate on the direct portion is ~15%. So even though the cost is paid in the form of ads, the equivalent take rate OTAs pay Google is effectively ~15%.

An agent charging 2%, 5%, or eventually 10%+ of GMV is therefore not necessarily introducing a new cost. It may simply be repackaging an existing acquisition cost from CPC into CPA / take rate. And agents @Muse will probably start cheap.

3/ What holds true no matter what (pre- or post-agentic world):

A. Owning top-of-funnel customer intent = pricing power. Losing direct traffic means losing much more than the immediate transaction.

B. Commerce winning formula (is always) = cheaper, faster, better.

++
A more verbose version: robonomics.substack.com/p/agentic-commerce-dee…
Harry Stebbings @HarryStebbings
Amazon is right to block Muse.

“One, you do not get any revenue from your ad business, and Amazon’s ad business is now larger than their e-commerce profits.

The second thing is the basket size gets reduced. If I do this, I just order the thing.

If I block them, they will probably come to me anyway, because I am Amazon. So I have leverage.” @rodriscoll

Love to hear your thoughts @juokaz @FredaDuan @scotwingo @harleyf
♥ 224 · ⟲ 26 · 👁 85.1KView on X ↗
More in Business & Markets

Michael Burry Warns Circular AI Financing Among Eight Firms Could Unravel

Michael Burry Warns Circular AI Financing Among Eight Firms Could Unravel

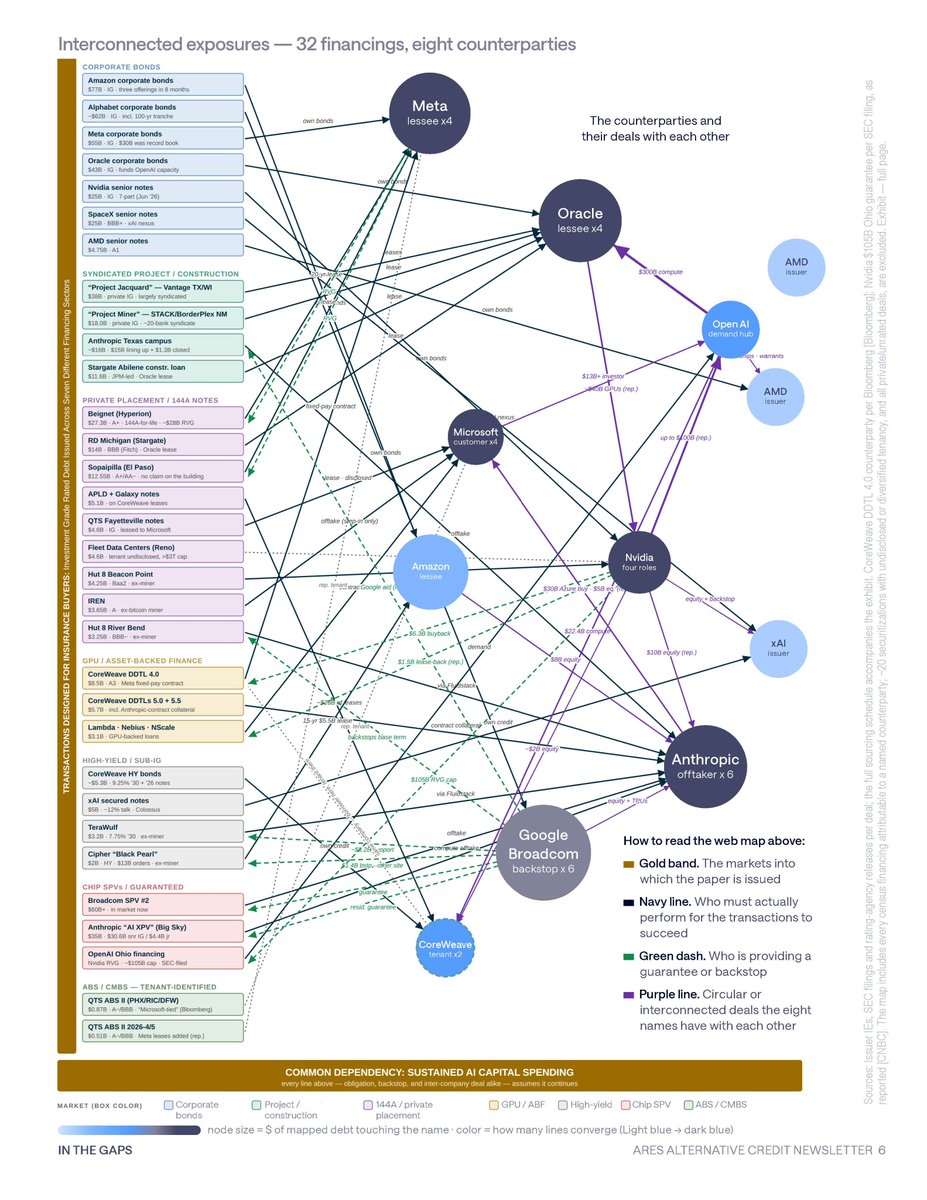
A tracker account relays Michael Burry's view that $573 billion in AI financing over the past year runs through eight companies that lend to, guarantee and buy from one another. Burry compares the setup to the 2000 telecom fiber bust and warns guarantees could be called if AI revenue disappoints.

Original post · 1 min read
Breaking: Michael Burry says the AI boom is running on one giant loop and time is running out

Here's his breakdown:

1. Burry shared a report from Wall Street lender Ares tracking $573B of AI financing from the last 12 months

2. All of it runs through just 8 companies: Meta, Oracle, Microsoft, Amazon, OpenAI, Anthropic, Broadcom and Nvidia

3. They lend to each other, guarantee each other's debt and buy from each other, so one company's loan is backed by another company's promise to keep spending

4. Every deal depends on one thing: AI spending never slowing down

5. If AI revenue disappoints for even one season, the guarantees could all get called at once, right when the companies backing them are at their weakest

6. Burry says it's the same circular financing that turned the 2000 telecom fiber boom into a bust

Burry claims the stock market in the first stage of grief and the crash is soon
♥ 4.6K · ⟲ 1.3K · 👁 343.9KView on X ↗

Navy Pays Anduril $2.9 Billion as U.S. Submarine Capacity Lags

The post argues the Navy turned to Anduril because only two U.S. yards build nuclear submarines and deliver far below the required rate, with China's shipbuilding capacity vastly larger. Anduril is investing $3.7 billion in a new Sparrows Point shipyard, Arsenal-2, with operations planned for 2030.

Original post · 1 min read
The US Navy just paid $2.9 billion to a company that has never built a submarine. Here's why they had no choice.

America has exactly two shipyards that can build nuclear subs. Electric Boat in Connecticut. Newport News in Virginia. The Navy needs two Virginia-class boats a year from them. They deliver 1.1.

Then it gets worse. Under AUKUS, America promised to sell Australia 3 to 5 Virginia-class submarines starting in the early 2030s. We signed a deal to export a product we can't build fast enough for our own fleet.

And the number behind all of it comes from the Navy's own intelligence office. China's shipbuilding capacity sits around 23 million tons a year. America's is about 100,000 tons. 230 times larger. One Chinese shipbuilder, CSSC, built more commercial tonnage in a single year than every American yard combined has built since World War II.

Both incumbent sub yards carry backlogs stretching past 2040, and the supplier base behind them shrank by thousands of companies after the Cold War. You cannot order your way out of that. There was physically no third option to call.

So the Navy invented one. Anduril adds $3.7 billion of its own money, breaks ground on the bones of Bethlehem Steel at Sparrows Point, once the largest steelworks on earth, shuttered in 2012, the yard complex that fed the fleet that won WWII. Hiring starts in 2029. Operations in 2030.

Four years from announcement to first output, and in American shipbuilding that counts as a sprint.
Anduril Industries @anduriltech
Anduril is investing $3.7B into Arsenal-2.
The next great American Shipyard.
♥ 236 · ⟲ 21 · 👁 18.1KView on X ↗

Huawei and Qualcomm Sign Broad Patent License, Cross-Licensing Deal

Huawei and Qualcomm announced a multi-year patent license agreement with cross licenses covering 5G, compute, AI and networking, plus Qualcomm's purchase of certain Huawei U.S. patents. Arnaud Bertrand calls it a notable outcome given U.S. efforts to cut Huawei out of those fields.

Original post · 1 min read
This is genuinely incredible: Huawei survived the most aggressive assault against a single company in modern history and is coming out the other side with the U.S. licensing its technology.

And ironically in the exact domains - 5G, AI, compute, networking - that the U.S. tried to cut Huawei out of.
Huawei @Huawei
Huawei and Qualcomm have announced a multi-year, broad patent license agreement that includes cross licenses to the companies' patent portfolios across a range of fields, including 5G, compute, AI, and networking, together with Qualcomm's purchase of certain Huawei U.S. patents.
♥ 5.8K · ⟲ 1.1K · 👁 161.0KView on X ↗

a16z Argues Flexible Data Centers Could Bypass Texas Grid Queue

a16z Argues Flexible Data Centers Could Bypass Texas Grid Queue

a16z's Ryan McEntush argues that data centers agreeing to curtail power during peak hours can connect to congested grids sooner. He cites Texas's queue growing to 474 GW, about 90% of it data centers, and estimates 100 GW of flexible capacity could be added without new plants.

Original post · 1 min read
Left: Texas's grid only maxes out about 200 hours a year, roughly 2% of the time.

Right: New data centers that agree to cut back during peak hours can skip the wait for more capacity. US grids could add 100 GW of them without building a single new plant.

a16z's @rmcentush on how flexible data centers get onto the grid sooner: a16z.news/p/why-texas-is-making-data-centers
Ryan McEntush @rmcentush
Why Texas Is Making Data Centers Wait — At the end of 2024, Texas’ grid operator had 63 GW of large new customers in its queue. By this June, that figure reached 474 GW, more than five times record peak demand, about 90% of it data centers.
♥ 122 · ⟲ 23 · 👁 19.4KView on X ↗

Larry Ellison Signs $40.4 Billion Guarantee for Warner Bros. Deal

Aakash Gupta reports that Larry Ellison signed a $40.4 billion personal guarantee to back the Ellison family's roughly $111 billion acquisition of Warner Bros. Discovery after Paramount's purchase, outbidding Netflix. The combined company, to be called Skydance, would include major studios, news networks and a 15% stake in TikTok's US entity.

Original post · 1 min read
A dad just signed a $40.4 billion personal guarantee so his son could buy Hollywood.

In 14 months, the Ellison family bought Paramount for $8 billion, then won a bidding war against Netflix for Warner Bros. Discovery at roughly $111 billion. Warner Bros, Paramount, CBS, HBO, CNN, DC, Nickelodeon, and TNT Sports now sit under one roof. Next week the combined company takes the name Skydance.

Netflix should have won. Warner's board had already signed an $83 billion deal with them and rejected the Ellisons twice, because the money sat in a revocable family trust the board called "illusory."

So Larry Ellison, 82 years old, answered with an irrevocable personal guarantee of $40.4 billion. One signature.

For scale, Larry has sold about $4.7 billion of Oracle stock this entire century. The guarantee was almost 9x everything he's cashed out in 25 years, backed by his 1.16 billion Oracle shares.

The merged streamer launches with around 207 million subscribers and $70 billion in projected annual revenue. And through Oracle, the family also holds 15% of TikTok's US entity.

Harry Potter, Top Gun, Batman, SpongeBob, Game of Thrones, CNN, CBS News, and a piece of TikTok's algorithm, all of it now answers to one family.
Valuetainment @valuetainment
JUST IN: HBO Max and Paramount+ are merging into a single streaming service.
♥ 545 · ⟲ 58 · 👁 77.9KView on X ↗

Valon Raises $150M Series D at $2.3B Valuation for Mortgage Software

Valon Raises $150M Series D at $2.3B Valuation for Mortgage Software▶

a16z reports that Valon raised a $150 million Series D at a $2.3 billion valuation after signing over $200 million in software deals, and describes how it became a regulated servicer before selling its platform to the industry.

Original post · 1 min read
.@Valon just raised a $150M Series D at a $2.3B valuation. Within six months of selling software, they signed over $200M in deals.

(And they're hiring!)

How the seven-year-old company got there:

- Mortgage is $13 trillion of consumer debt running on a system built before the internet, and no servicer will trust a new platform. So Valon became one.

- Co-founder Andrew Wang read every federal and state regulation, 18 hours a day for six months, and turned it into code.

- They ran their own servicer on the software until it hit 3x the industry's efficiency, sold that servicer to a larger mortgage company, and now sell the software to everyone else. One of the biggest servicers in the US is moving 4 million loans onto it, nearly 10% of the market.

Valon is hiring deployment strategists in NY and SF. Read more about their open roles: a16zjobs.substack.com/p/valon-just-raised-150m…

@xlindadu @wangandrewd
a16z @a16z
a16z's Angela Strange sits down with @Valon's Andrew Wang and Linda Du to unpack what it takes to rebuild the infrastructure underneath a $13 trillion mortgage market that still relies heavily on systems designed before the internet.

Linda and Andrew explain why Valon chose the hardest path: becoming a regulated mortgage servicer, translating decades of federal and state regulation into software, and proving the platform on its own loans before selling it to the industry. That foundation made Valon roughly 3x as efficient as traditional servicing and created the system of record it is now usi…
♥ 253 · ⟲ 22 · 👁 47.4KView on X ↗